





0102030405
The Impact of Global Raw Material Prices on Candle Filter Cost
2025-12-08
Anyone who's spent time in a process plant knows the sound—that steady hiss of a Candle Filter bank doing its job. It's a good sound, means production is moving. But lately, that sound has been getting more expensive to make. Not because of engineering changes, but because the steel mills in Rotterdam raised alloy surcharges, or because nickel futures spiked after a mining strike in Sudbury, or simply because the container ship carrying filter media got stuck outside Singapore for ten days.
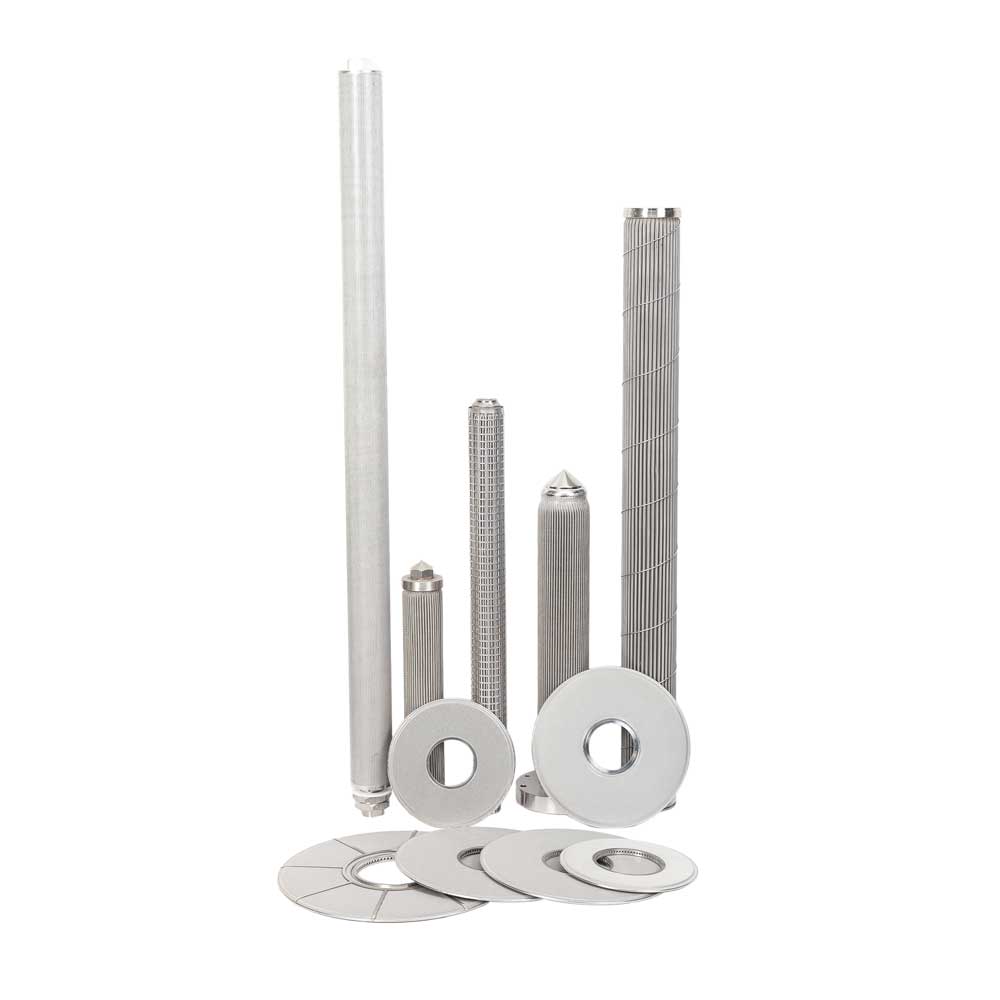
That's the reality we're dealing with. Candle Filters don't look complicated—just tubes of sintered metal or ceramic hanging in a housing. But every component is touched by global commodity markets, and those markets have been anything but quiet.
The stainless Steel Wire Mesh that forms the backbone of mostindustrial candle filters? That rolls off mills where the price moves weekly based on chromium contracts from South Africa and nickel inventories in Shanghai warehouses. A filter housing that cost a certain amount in March might jump 12 percent by June, even with the same design, same fabricator, same everything. We've seen it happen. One quarter, molybdenum prices climb because a single major supplier has a maintenance shutdown, and suddenly every high-temperature filter destined for a refinery in Houston or a chemical plant in Rotterdam carries a premium.
It's not just the obvious metals either. The gaskets that seal these units—those use specialized fluoroelastomers whose raw materials come from a handful of plants in Germany and Japan. When those plants face feedstock issues, lead times stretch from six weeks to fourteen, and spot prices become something you don't want to think about. The ceramic filter elements used in hot gas applications? They rely on alumina powders where China controls 60% of global supply. A policy shift in Beijing can ripple through to a maintenance manager in Ohio trying to get his unit back online before quarter-end.
What makes this particularly tricky for operations is the lag effect. Raw material prices change daily, but filter quotes are typically valid for 30 days. If you're planning a turnaround six months out, the price you budgeted might be a distant memory by the time you issue the PO. I've watched maintenance planners get burned when they based their Q4 budget on Q1 quotes, only to find the actual procurement cost 22% higher. That delta doesn't come from anyone getting greedy—it's the steel, the welding wire, the argon gas for TIG welding, all of it marching upward.
The regional angles matter more than most realize. Take the Middle East—harsh climate, demanding specs, but huge petrochemical investments. A solid candle filter supply chain there means sourcing housings locally from Saudi fabricators using Indian stainless steel, while filter elements ship from Europe. That mix helps balance cost and delivery risk. But it also means you're exposed to three different trade routes, three sets of tariff structures, and three currency fluctuations. The savings on freight can evaporate if the rupee moves against the dollar at the wrong time.
Southeast Asia tells a different story. The manufacturing hubs in Thailand and Vietnam are hungry for filtration equipment, but they're also close to China’s raw material production. That proximity cuts shipping time for base materials, but it also means you're competing with every other fabricator in the region for the same stainless steel coils. When China's construction sector revives and starts pulling tons of steel, the ripple hits your filter housing costs within weeks. Smart buyers there lock in quarterly supply agreements with mills, not because they want to speculate, but because they'd rather have predictable costs than gamble on spot markets.
The real gut punch comes when you think you've covered everything. You've hedged your steel cost, you've got a six-month contract on gaskets, you've even sourced alternative filter media from a second region. Then the welding rods for assembling the housings jump 40% because the manganese used in their coating comes from a region with new export taxes. Or the cost of argon shielding gas spikes because air separation plants are running full tilt to supply semiconductor fabs. These second-tier raw materials never make the headlines, but they show up on the final invoice.
This is where experienced procurement teams shift their thinking. They stop chasing the lowest bid and start building relationships with manufacturers who have material-sourcing intelligence. The good ones can tell you which mills are offering what surcharge structure next month, which ports are seeing demurrage pile up, which alloys are being substituted where. That information is worth more than a 3% price break from a supplier flying blind.
Vertical integration helps, but only to a point. A filter manufacturer that controls its own sintering operation still has to buy metal powder. One that extrudes its own tubes still tracks nickel prices. The real advantage comes from flexibility—having designs that can accept substitute alloys without a full requalification, or modular housings where you swap components based on material availability. We've seen leading manufacturers redesign their end caps to use less exotic steel grades without sacrificing pressure ratings, simply because they saw the price trend six months ahead.
Long-term contracts used to be the safe harbor. You'd lock in a price for a year and sleep well. But in today's market, suppliers are reluctant to take on that risk unless you commit to serious volumes. Even then, they build in escalation clauses tied to metal indexes. The art is negotiating which index—LME nickel, CRU stainless, or something regional—and how often it resets. Some buyers are pushing for quarterly adjustments instead of monthly, betting that volatility smooths out over 90 days. Others take the opposite tack, preferring monthly resets to avoid getting stuck on a high plateau.
Inventory strategy is another lever, but it's expensive. Holding six months of filter elements ties up capital and warehouse space. Yet for critical applications—say, a gas plant where downtime costs $200,000 an hour—that insurance policy looks cheap. The trick is figuring out which SKUs deserve that treatment. Generally, it's the odd sizes, the specialty alloys, the ones with long lead times. Standard 316L stainless elements? Those you can get in weeks. But the Hastelloy C-276 candles for that corrosive service? Maybe you keep a few on the shelf, even if they cost twelve times more.
Process efficiency on the manufacturer side matters too. A fabricator who can cut waste by 5% on stainless steel sheet metal effectively insulates you from a 5% price increase. Same with welding—better automation means less rework, which means less material burned up in scrap. These aren't things you see in a spec sheet, but they show up in the final cost and delivery time. Ask your supplier about their material yield rates; if they don't know the number, that's a red flag.
The conversation is changing. It used to be about micron ratings and pressure drop curves. Now it's about supply chain mapping and material substitution studies. A good technical discussion today includes questions like: "If this alloy jumps 30%, what's your fallback material?" or "Which of your feedstocks have you dual-sourced?" That's not because buyers are paranoid—it's because they've been burned before.
At the end of the day, candle filters are still one of the most reliable workhorses in industrial filtration. They handle hot gases, corrosive chemicals, sticky polymers, and come back for more. But the economics behind them have gotten complex. The buyers who navigate this best aren't the ones with the biggest budgets—they're the ones who understand that a filter is just steel, powder, and rubber, and that knowing the story behind those materials is as important as knowing the differential pressure across them.
